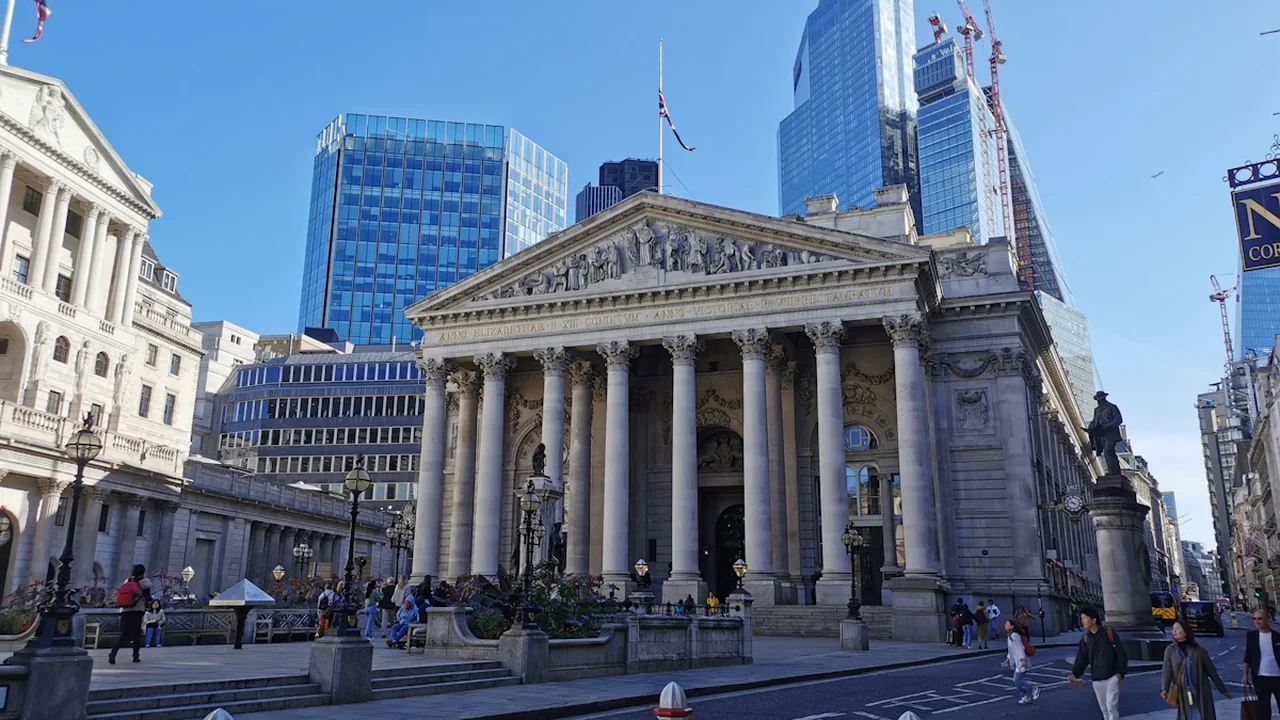
The Bank of England has scheduled its next Monetary Policy Report and interest-rate announcement for 17 September 2026, putting mortgage borrowers, savers and other UK households on notice for a potentially important change in borrowing costs. The key question is whether the Monetary Policy Committee will lower Bank Rate from the level in force immediately before that announcement.
A reduction is possible, but the official calendar confirms only when the decision is due—not what the MPC will decide. Inflation, wage growth, economic activity and policymakers’ public assessments could all alter the balance before the vote.
By the GlobeBids Economy Desk | Published 15 August 2026
Read also: ONS July CPI: Will inflation be 3% or higher on August 19?
The September decision at a glance
- Question: Will the Bank of England lower Bank Rate on 17 September 2026?
- Deadline: The forecast closes before the scheduled announcement that day.
- YES: The announced rate is lower than the rate immediately beforehand.
- NO: Bank Rate is unchanged or increased.
- Official result: The Bank of England’s Bank Rate page and MPC announcement will determine the outcome.
The comparison is deliberately narrow. Earlier reductions during 2026 would not automatically produce a YES result; only the change announced at the September meeting counts.
The case for a September rate cut
The MPC could reduce Bank Rate if the evidence available before the meeting shows that inflationary pressure is becoming less persistent. The most relevant indicators include headline and core consumer-price inflation, services inflation and measures of underlying price growth.
Wage data will also matter. Slower growth in regular earnings could reassure policymakers that domestic cost pressure is easing, particularly if it is accompanied by weaker hiring demand or rising spare capacity in the economy. A single monthly reading would be less persuasive than a consistent direction across several releases.
Economic weakness could strengthen the case for a cut. Softer household spending, subdued business investment or a cooling labour market would raise the cost of keeping monetary policy restrictive. The MPC would still need to judge whether lower demand was reducing inflation quickly enough to justify action.
A YES outcome therefore becomes more plausible if several developments align:
- Services and underlying inflation continue moving lower.
- Regular wage growth cools without a renewed price shock.
- Employment and activity indicators show weakening demand.
- MPC communications describe inflation persistence as less severe.
- The previous vote reveals growing support for lower rates.
None of those signals alone would guarantee a reduction. The committee sets policy collectively, and its assessment can change when new data or forecasts arrive.
Why the MPC could hold—or increase—Bank Rate
A NO outcome includes both an unchanged rate and an increase. A hold may be more likely if inflation is falling but remains inconsistent with a sustainable return to the target, or if policymakers want more evidence before easing again.
Persistent services inflation or strong wage growth would be particularly important. These measures can indicate that domestic inflation is embedded even when falling energy or goods prices reduce the headline rate. The MPC could also pause if earlier rate changes had not yet passed fully through the economy.
An increase would represent a more restrictive response. It could enter consideration if inflation accelerated materially, wage pressure strengthened or sterling weakness threatened to raise import costs. An unexpected energy or supply shock could complicate the decision as well.
The official calendar is not policy guidance, and the Bank of England pages cited here do not promise a cut. Market-implied expectations can show how investors are positioned, but they are neither an MPC commitment nor a substitute for the published decision.
Variable-rate mortgages could respond first
A September cut would be most directly relevant to borrowers whose mortgage rates move with Bank Rate. Tracker mortgages generally follow a specified benchmark plus a lender margin, so repayments may decline when the contractual adjustment takes effect.
Standard variable-rate mortgages are less mechanical. A lender may lower its rate after a Bank Rate cut, but the size and timing depend on its own pricing decision and the borrower’s terms. Customers should check their mortgage agreement rather than assume that the full reduction will be passed through immediately.
Remortgaging depends on more than one MPC vote
Fixed mortgage offers are influenced by expectations for rates over several years, lenders’ funding costs, swap rates, competition and borrower risk. Deals can therefore become cheaper before an official cut—or move higher even when Bank Rate is unchanged.
Borrowers approaching the end of a fixed term should compare the cost of securing a deal early with the flexibility of waiting. Arrangement fees, early-repayment charges, loan-to-value bands and the lender’s product-transfer options can outweigh a small difference in the headline rate.
A NO result would not mean every mortgage offer must rise. It would mean only that the MPC did not reduce Bank Rate at this particular decision.
Savings, consumer credit and sterling face different effects
A cut would usually put downward pressure on easy-access savings rates, although providers do not all reprice at the same speed. Fixed-term savings accounts may already reflect expectations for future policy, while competition for deposits can keep some rates elevated.
Savers should compare the annual equivalent rate, access restrictions, introductory bonuses and Financial Services Compensation Scheme eligibility. Moving money solely in response to the announcement could be unnecessary if an existing fixed rate remains competitive and protected by its original term.
Consumer borrowing may respond unevenly. Some personal loans and car-finance products are fixed when the agreement begins, while credit-card rates depend on provider pricing and borrower circumstances. A quarter-point Bank Rate change does not translate automatically into the same reduction across every form of credit.
Sterling could weaken if a cut is less expected or more dovish than investors anticipated, potentially increasing the sterling cost of imports. It could strengthen after a cut if the decision is accompanied by a firmer economic outlook or if investors had expected a larger reduction. The reaction depends on the gap between the decision and prior expectations, not simply the direction of Bank Rate.
The evidence that could change the September decision
The Bank of England’s official Bank Rate page identifies the rate set by the MPC and records its change history. For resolution purposes, that page establishes the rate in force immediately before the September announcement and the new rate, if any, announced afterward.
Inflation and wages remain the central tests
The latest official UK consumer-price and earnings releases available before the meeting will be crucial. Readers should distinguish headline inflation from core and services measures, and total pay growth from regular earnings, because volatile components can give different impressions of underlying pressure.
The clearest policymaker signals will come from attributable Bank of England material: the previous MPC vote split, meeting minutes, the Monetary Policy Report and named speeches or testimony. Even an explicit preference expressed by one member would not bind the full committee or settle a later vote.
Other useful checks include labour-market conditions, retail activity, business surveys, inflation expectations, energy prices and sterling. Their importance lies in how they affect the MPC’s inflation forecast and assessment of economic slack.
Until those releases and communications are available, a balanced forecast is more defensible than treating a cut as certain. The public evidence currently establishes a firm decision date and an objective test, but not the direction of the vote.
How the forecast will be resolved
The forecast resolves YES if the Bank of England announces a Bank Rate on 17 September 2026 that is lower than the rate in force immediately before the announcement. It resolves NO if the rate is unchanged or increased.
The Bank of England’s published announcement and official rate history are controlling. Revisions to commentary, mortgage pricing or market expectations do not affect the result.
If the scheduled decision is postponed, the forecast remains pending until the replacement decision. The editorial long-stop is 31 December 2026 at 23:59 London time; if no replacement decision has occurred by then, the forecast closes without a YES or NO determination. The next decisive check is the MPC announcement published on the Bank of England website.
Source: Bank of England
Context & actions About this article
Source check Forecast resolution
The result will be determined by comparing the official Bank Rate immediately before and after the scheduled MPC announcement.
- Confirm the pre-decision rate on the official Bank Rate history page.
- Check the MPC announcement scheduled for 17 September 2026.
- Resolve YES only if the announced rate is lower.
- Keep the forecast pending if the decision is formally postponed.
- Source
- Bank of England MPC calendar
- Scope
- United Kingdom
- Updated
- 2026-08-15 17:42
Source check
Report a trust issue
Send a clear signal to community moderation if the source, facts or context need review.


Comments