By GlobeBids Editorial Desk | 13 August 2026
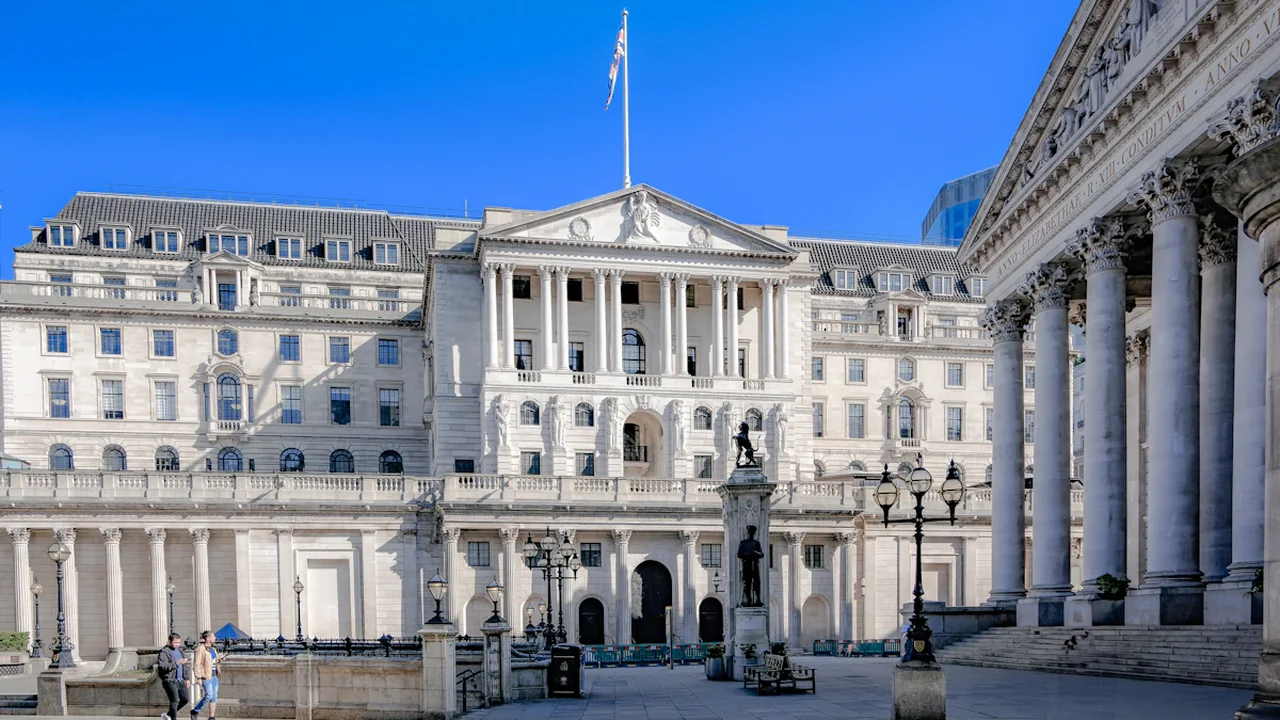
The Bank of England’s September 2026 Monetary Policy Committee decision will determine whether Bank Rate is lowered from its level immediately before the announcement. Bank Rate is set by the Bank of England as a central tool affecting borrowing and saving conditions, while the MPC is the committee responsible for monetary policy decisions. The result matters to mortgage holders, savers, businesses and renters, and this forecast closes when the official decision is published on 17 September 2026.
The September 2026 Bank Rate decision at a glance
- Will the MPC announce a lower Bank Rate at its September 2026 decision?
- Decision deadline: 17 September 2026.
- YES: The announced Bank Rate is lower than the rate in force immediately before the decision.
- NO: The MPC holds Bank Rate unchanged or raises it.
- Decisive record: The Bank of England’s September Monetary Policy Report and policy decision statement.
The available official material establishes who makes the decision and why Bank Rate matters, but it does not itself provide a current inflation reading, wage data, growth forecast or MPC voting split. Those missing signals are central to the direction of the September outcome. The evidence supports a clear resolution method, not a certainty about whether the committee will cut.
Bank Rate is set by the MPC, not by mortgage lenders
The Bank of England describes Bank Rate as the interest rate it sets to influence the wider economy. Changes can feed through to borrowing and saving conditions, but Bank Rate is not the same thing as the rate displayed in every mortgage offer or savings account.
The Monetary Policy Committee is responsible for setting monetary policy, including Bank Rate. Its decision is made collectively, so the headline rate is the product of a committee vote rather than an automatic response to one economic statistic.
That distinction matters for this September forecast. A lower Bank Rate would be an official policy change, but households may see different effects depending on the type of financial product they hold and the terms they agreed when they opened it.
Why a rate cut could matter for mortgages, savings and rents
A reduction in Bank Rate can be meaningful for household budgets, yet the timing and size of the effect vary.
Mortgage payments may not move together
Borrowers on tracker mortgages or some variable-rate products may see their interest costs adjust more directly after a Bank Rate move, subject to their lender’s terms. People on fixed-rate deals usually keep their agreed rate until the fixed period ends.
New mortgage offers are also not a simple mirror of Bank Rate. Lenders consider expected future policy, funding costs, competition and their own pricing decisions. That means a September cut could improve some available offers, while other rates may have already changed in anticipation of the decision. Recent mortgage approvals can also provide context for how the wider housing market is responding.
For borrowers approaching a remortgage, the practical question is not only whether the MPC cuts. It is also what rate is available when their current deal ends and whether a new offer can be secured before then.
Savers could receive less interest over time
Savings accounts are affected in the opposite direction. A lower Bank Rate can put downward pressure on variable savings returns, though providers set their own account rates and may move at different times.
Savers relying on interest income should check the rate, access conditions and notice requirements on their specific account after any MPC decision. A rate cut does not automatically mean every savings product changes on the same day.
Renters may feel an indirect effect
Renters do not pay Bank Rate directly, but landlords with mortgages may face refinancing costs when their existing deals expire. Lower borrowing costs could reduce one source of pressure on a landlord’s finances. That does not guarantee lower rents, since rent levels also reflect local supply, tenant demand, maintenance costs and other expenses.
Inflation remains the central test for a September cut
The MPC’s policy task is tied to bringing inflation back to its target sustainably. A cut is more plausible when the committee judges that inflationary pressure is easing sufficiently and that maintaining a higher Bank Rate would restrain the economy more than needed.
The word “sustainably” is important. A single favourable inflation release may not settle the question if other measures suggest persistent price pressure. The committee can examine a broader picture that includes services prices, pay growth, household demand, business conditions and its own forecasts.
The September statement should therefore be read for more than the headline rate. The accompanying explanation can show whether the MPC sees inflation risks as easing, balanced, or still tilted upward.
The vote can show how firm the decision is
The MPC vote is a useful clue to the committee’s internal balance. A unanimous decision can signal broad agreement, while a split vote can reveal different assessments of inflation or economic weakness.
A cut backed by a narrow majority would still resolve this forecast as YES. Equally, a hold reached after disagreement would resolve NO, but could indicate that a future cut remains under discussion. The binary outcome is simple; the policy message around it may not be.
The path to YES: enough confidence that inflation pressure is easing
A September rate cut would be consistent with an MPC view that restrictive policy is no longer needed at the prior level. The committee could reach that conclusion if incoming data and forecasts give it greater confidence that inflation will return to target without keeping Bank Rate unchanged.
A YES result would not necessarily signal that borrowing will become cheap. It would indicate only that the official Bank Rate was reduced relative to its pre-decision level. The size of any move, the wording of the statement and the outlook for further decisions would shape how lenders, savers and businesses interpret it.
For households, the immediate value of a YES outcome may be greatest as a prompt to compare options. Mortgage customers can check whether their lender has changed variable rates or whether a new fixed offer suits their timeline. Savers can compare their account’s revised return with alternatives, taking notice periods and withdrawal limits into account.
The path to NO: a hold or increase still counts against the forecast
The forecast resolves NO if the MPC leaves Bank Rate unchanged or raises it. A hold would mean the committee did not announce a lower rate at the September decision, even if it acknowledges that a reduction could be considered later.
The MPC could prefer a hold if it judges inflation pressure to be too persistent, if forecasts remain uncertain, or if it needs more evidence before changing policy. It could also decide that the existing Bank Rate is appropriate while it assesses how earlier decisions are affecting the economy.
An increase is also a NO outcome because Bank Rate would not be lower than it was immediately before the announcement. The resolution does not depend on the committee’s tone, market expectations or the movement of consumer mortgage offers; it depends on the published Bank Rate decision.
What to check when the Bank of England publishes its decision
On 17 September, readers should begin with the Bank of England’s policy decision statement and Monetary Policy Report. Four details will put the rate decision in context:
- The new Bank Rate, compared with the rate immediately before the announcement.
- The MPC voting breakdown.
- The committee’s assessment of inflation returning to target.
- Any indication of how it views future policy decisions.
Consumers should then check their own provider rather than assuming an instant pass-through. Mortgage holders can review the terms of their tracker, variable or fixed deal. Savers can check whether their account rate has changed. Renters should treat the decision as one factor in landlords’ costs, not as a direct forecast for local rents.
The September outcome will be resolved by a public, dated decision: a lower Bank Rate is YES; an unchanged or higher Bank Rate is NO. Until the MPC publishes that statement, the responsible reading is that both outcomes remain possible and that the committee’s inflation assessment is the key factor to watch.
Source: Bank of England
Context & actions About this article
Source check Decision basis
The outcome depends solely on whether the MPC publishes a lower Bank Rate on 17 September 2026.
- Read the September 2026 MPC policy decision statement.
- Compare the announced Bank Rate with the rate in force immediately before the decision.
- Check the MPC voting breakdown.
- Read the committee’s inflation assessment in the Monetary Policy Report.
- Source
- Bank of England: Bank Rate
- Scope
- United Kingdom
- Updated
- 2026-08-13 13:44
Source check
Report a trust issue
Send a clear signal to community moderation if the source, facts or context need review.


Comments